
The library
Every guide we’ve written
46 free guides on investing, personal finance, real estate, and crypto — written for younger readers building financial literacy from zero.
New to some of the terms? The money glossary explains 55 of them in plain English.
Personal Finance
Where Can First-Time Buyers Afford a Home? 100 US Metros and Every UK Region (2026)
A starter home takes 47.9% of a young household's income in Los Angeles and 9.9% in Jackson, MS. See where 100 US metros and 12 UK regions rank.
Investing
What a Recession Actually Does to Your Money in Your 20s (And the 3 Moves Worth Making Before One)
Nobody will tell you a recession started until months after it began. The committee that dates US recessions has taken anywhere from four to twelve months to make the call, so every plan built on reacting to the news fires late. Which is fine, because at 24 the thing a downturn threatens isn't the portfolio you won't touch for forty years. It's the paycheck that covers rent next month, and workers aged 20 to 24 already carry roughly double the unemployment rate of people aged 35 to 44. Here's what the data says a recession really costs someone your age, the three moves worth making before one arrives, and the two instincts that quietly do the most damage.
Personal Finance
Your Savings Rate, Not Your Salary, Decides When You Can Stop Working
A raise does nothing for your retirement date. Spend it and you've moved neither number that matters. Save it and you've moved both at once, because the finish line is a multiple of what you spend. Two people on $70,000 can finish 19 years apart on that difference alone.
Investing
Can You Trust AI for Financial Advice? Seven Chatbots Gave Seven Answers
Your chatbot is guessing, and it sounds exactly the same as when it isn't. Researchers gave seven AI tools an identical household profile and asked how much the family should hold in emergency savings. The recommendations came back anywhere from about $21,000 to $37,500. Ask the same tools for a safe retirement withdrawal rate, though, and they almost all said 4%. Here's what that split tells you about which money questions AI is safe on, the one tool that cut its stock recommendation in half when only the race of the person changed, and the ninety-second test to run before you act on anything a chatbot tells you.
Investing
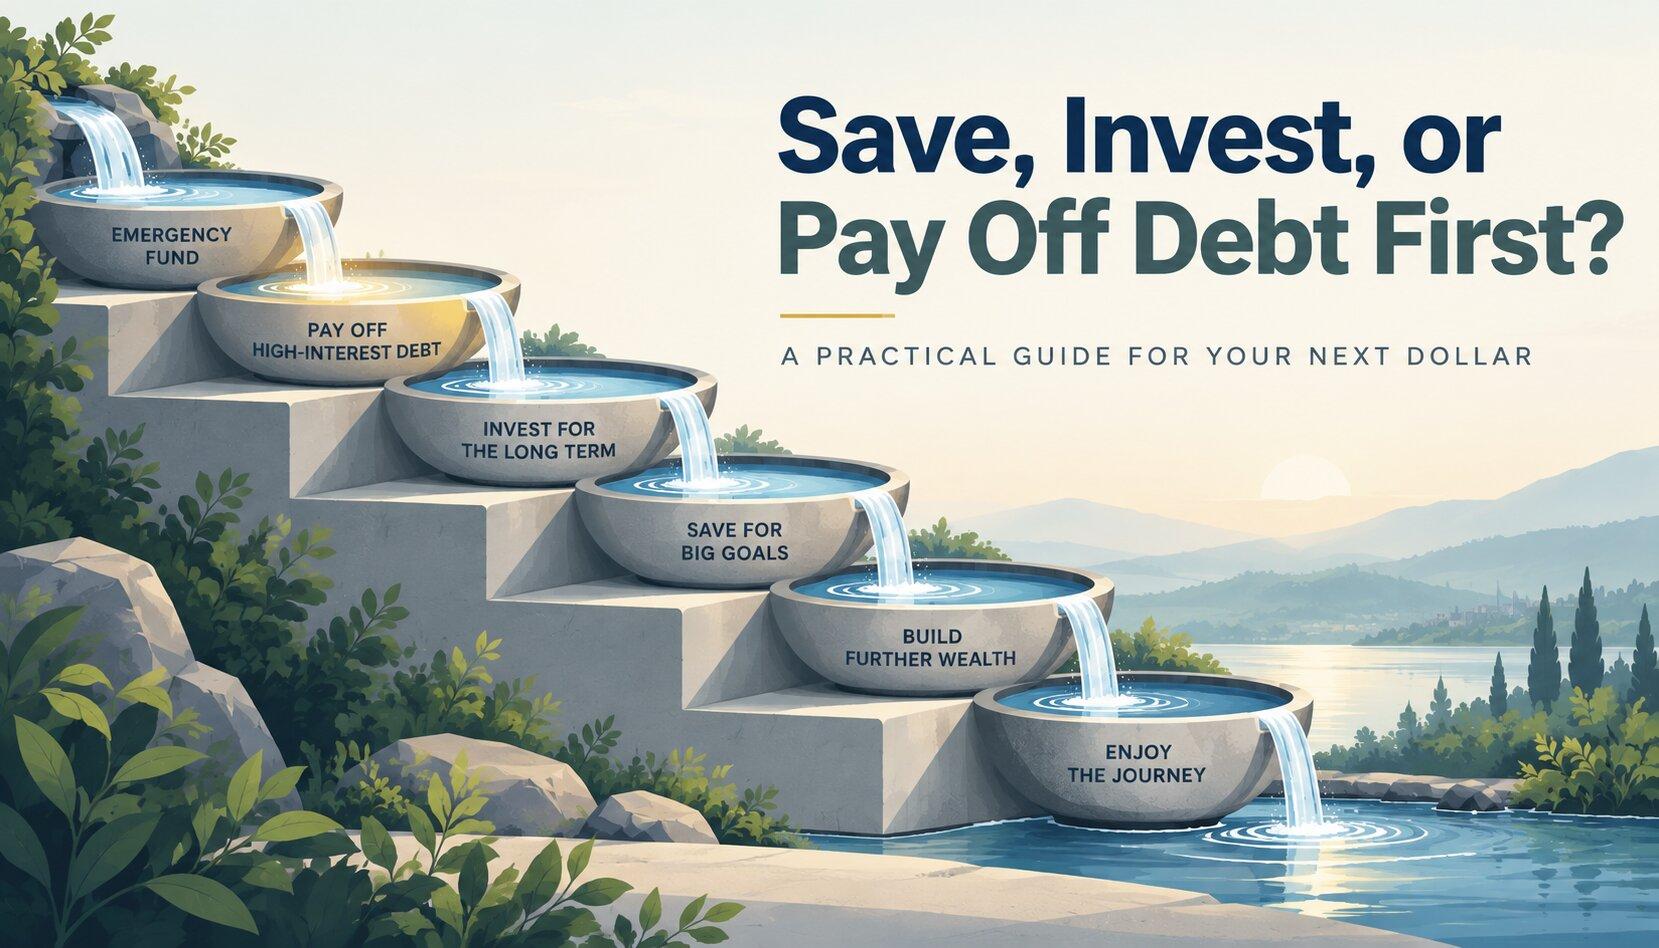
Save, Invest, or Pay Off Debt First? The Financial Order of Operations
Your employer match beats paying off a credit card. Most beginner guides put the emergency fund first, a few open with insurance deductibles, and that is why nobody agrees on step one. The tiebreaker is simpler than the arguing suggests. Rank every dollar by what it earns you, then pull just enough cash forward that a surprise never pushes you back onto the card. Here is the full seven-step order with the 2026 contribution limits, one worked example on a $55,000 salary that quietly runs out halfway through step five, and the two moments when breaking the order is the right call.
Investing
How Much of Your Portfolio Should Be in Stocks at Your Age? (And Why '100 Minus Your Age' Is Outdated)
Your retirement got three and a half years longer. The rule that tells you how much to hold in stocks was calibrated against a 1980 retirement, and it has not moved since. A 65-year-old back then could expect 16.9 more years of life. Today it's 20.5, and "100 minus your age" still says exactly what it said forty years ago. Here's where the rule actually broke, the 30-point gap between it and a real glide path at 40, and the one swap that fixes it without turning your portfolio into a hobby.
Personal Finance
5 Numbers Worth Checking Before Summer Ends (A Mid-Year Financial Review That Takes 10 Minutes)
Americans are saving 2.7% of their income. That's the June 2026 figure from the Bureau of Economic Analysis, and it's a fraction of what every budgeting rule assumes. Most people have no idea where they sit against it, because almost nobody actually calculates their own savings rate. Half the year is gone, which makes right now the cheapest possible moment to find out. Here are the five numbers that make up a real mid-year review, the two-minute method for pulling each one, and the rule for deciding which single number is worth acting on before January.
Investing
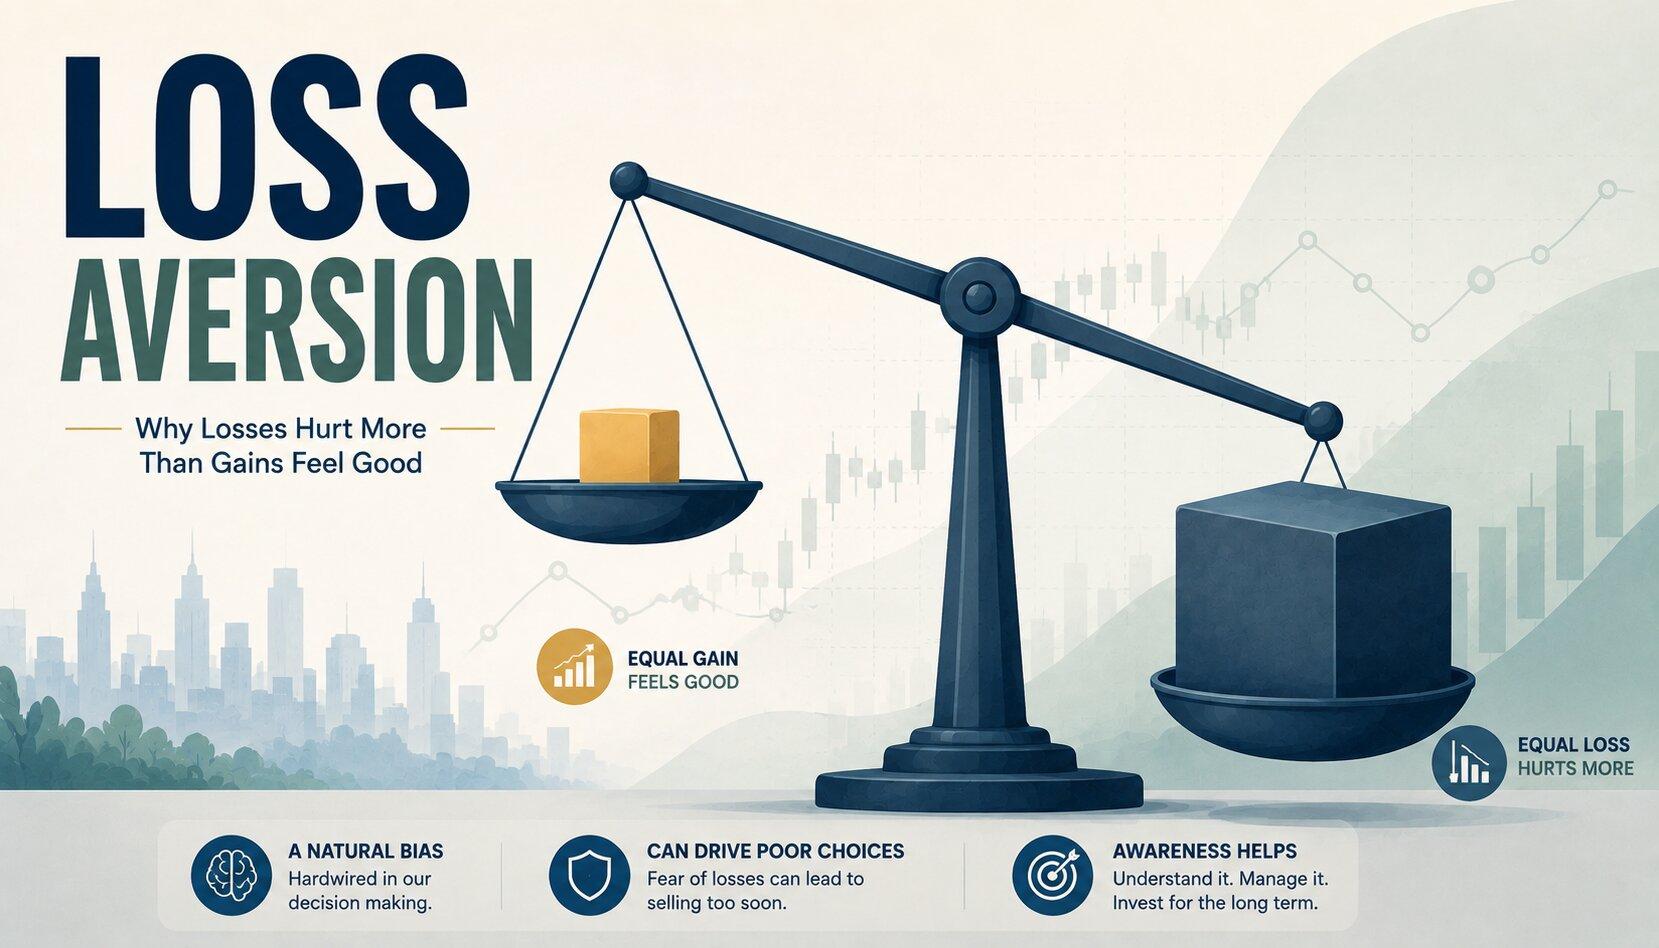
Why a $100 Loss Hurts Twice as Much as a $100 Gain Feels Good (And Why It's Quietly Costing You)
Your brain charges you twice as much for a loss as it pays you for a gain. That single bit of wiring is why smart people sell at the bottom, cling to their worst stock for years, and hide in cash they can't retire on. It even has a price tag: Morningstar pegs the average investor's self-inflicted cost at about a point of return every year. The strange part is that knowing all this doesn't fix it. Here's where the 2:1 number comes from, what it quietly costs in real dollars, and the one boring habit that shrinks the damage more than willpower ever will.
Personal Finance
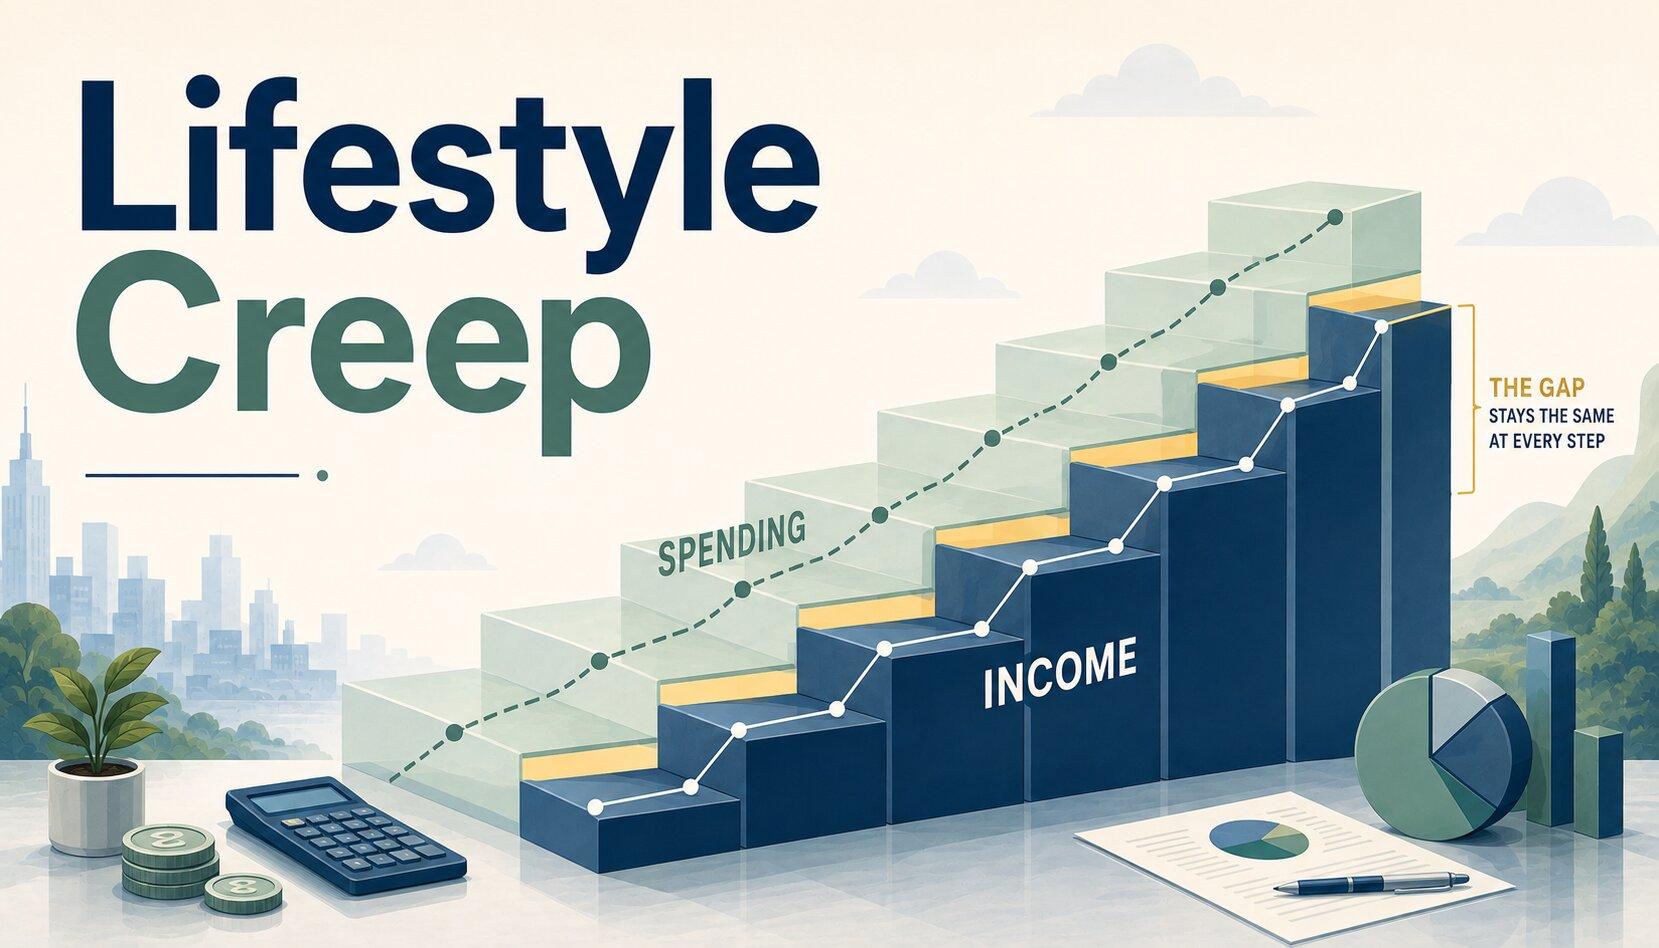
The Lifestyle Creep That Quietly Eats Your Next Raise (And the 50% Rule That Stops It)
Your next raise probably won't make you richer. Not because it's too small, but because your spending quietly rises to match it. Economists call this lifestyle creep, and it's a big reason the US savings rate hasn't risen even as paychecks grew. The fix isn't more willpower, it's a rule that captures part of the money before you can spend it. Here's the 50% rule, the brain science that makes it necessary, and what half of a single raise could quietly grow into over 30 years.
Personal Finance
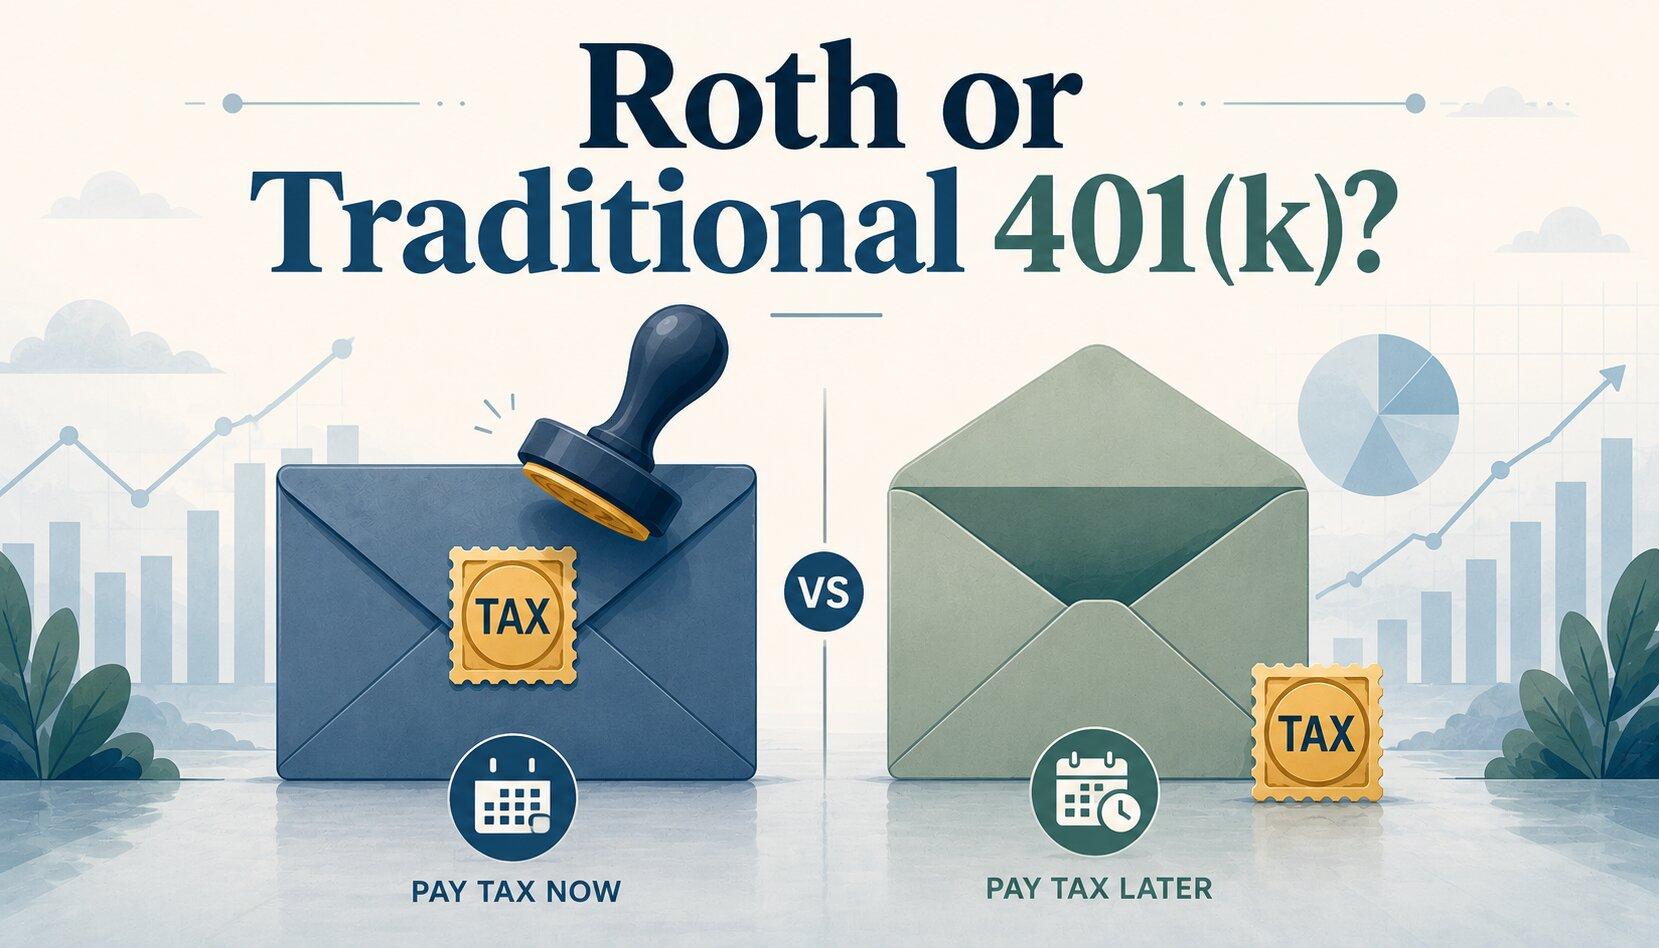
Roth or Traditional 401(k)? The Tax-Bracket Question That Settles It
Your first 401(k) form has a trick question on it. Roth or Traditional doesn't change your salary, your investments, or how much you can save. It only changes when you hand the IRS its cut. Most guides list ten factors and quietly never answer the question. Here's the one tax-bracket comparison that actually settles it, a worked example with real 2026 numbers, and the three situations where the simple rule bends.
Personal Finance
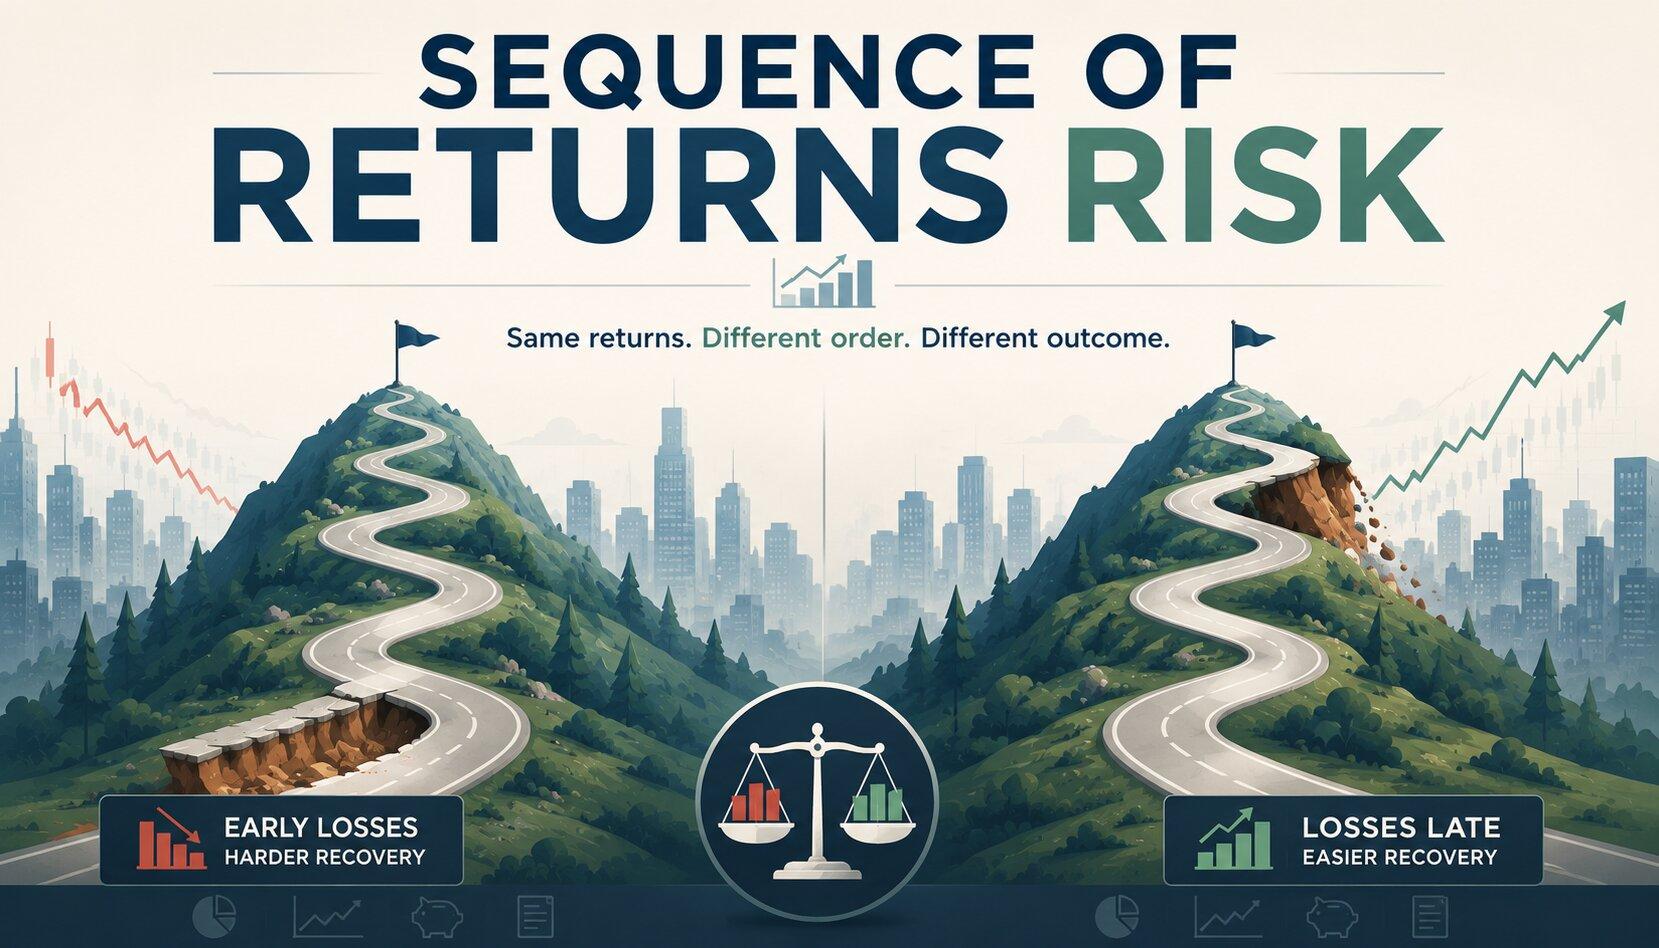
The Quiet Retirement Risk Most Investors Ignore (Until It's Too Late)
Your retirement date may matter more than your returns. Sequence of returns risk is the quiet reason two people with identical average returns can end up in completely different places. It only bites hard in the roughly ten years around the day you stop working. Before then, a crash is a discount, not a disaster. Here's what it really is, who should actually worry about it, and the three cheap, boring fixes that beat panic every time.
Personal Finance
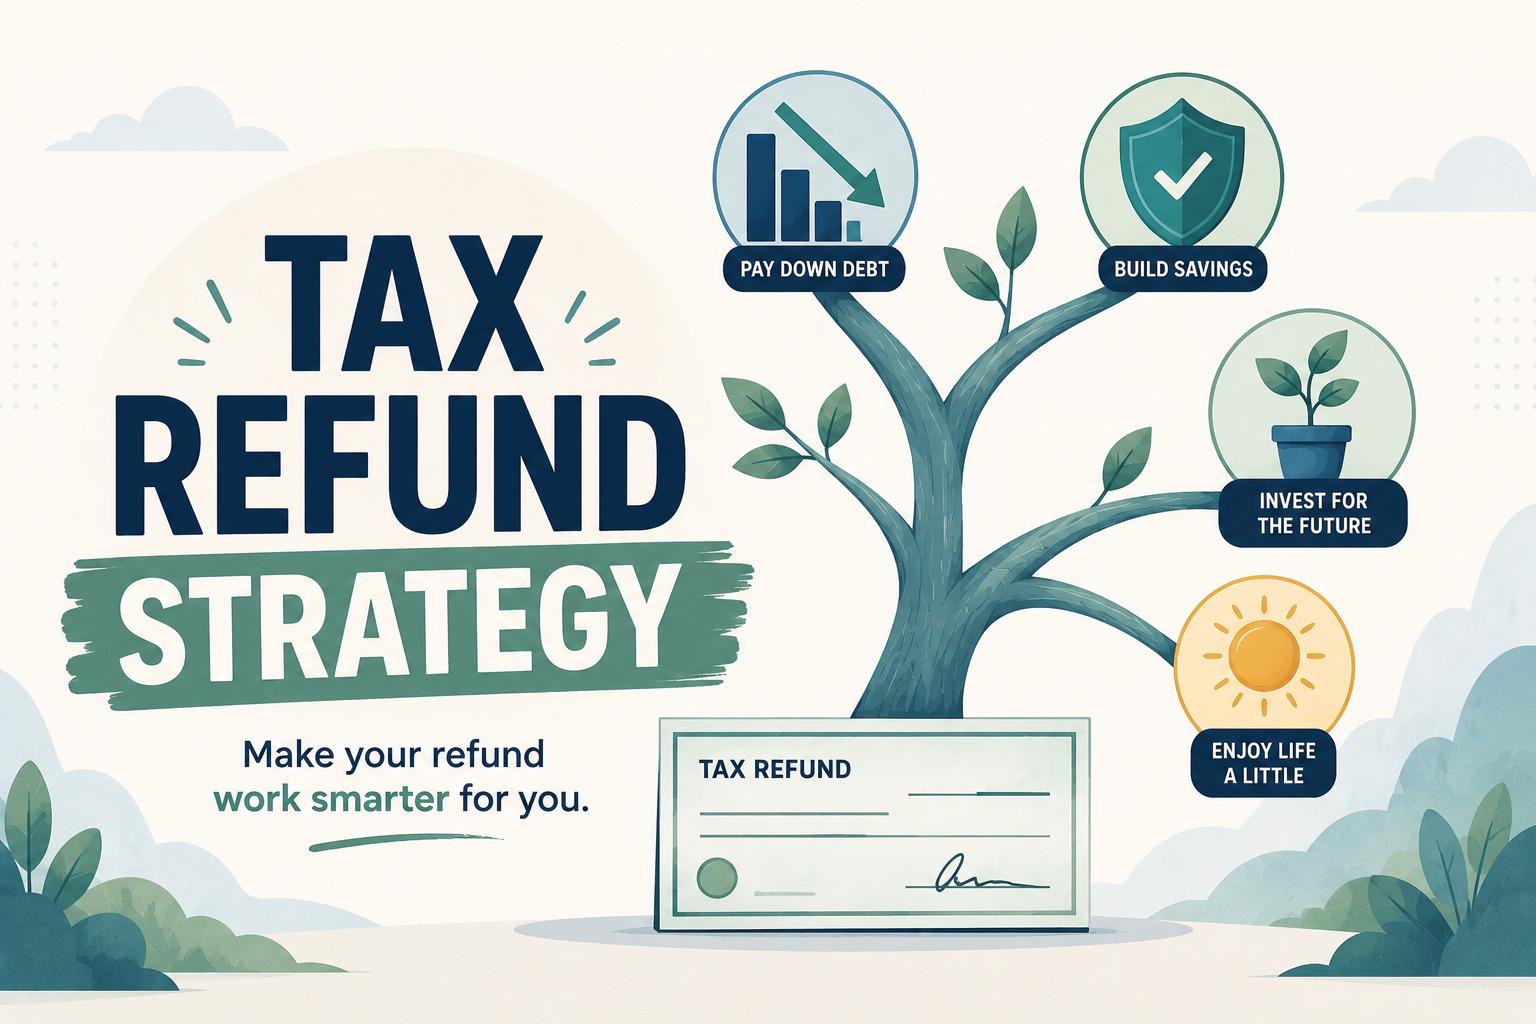
What to Do With Your Tax Refund Before You Spend It (A 5-Step Decision Tree for Your 20s and 30s)
Your tax refund was never a bonus. It's your own paycheck, handed back after the government held it interest-free for a year. The average refund topped $3,000 this year, and most of it disappears within weeks because the brain treats found money differently. Spend it on autopilot and a $3,000 check buys you nothing you'll remember. Here's the five-step decision tree that puts a refund to work: the debt to kill first, the retirement deadline most people miss, and the one slice you're allowed to spend guilt-free.
Showing 1 to 12 of 46 articles