Investing
How Much of Your Portfolio Should Be in Stocks at Your Age? (And Why '100 Minus Your Age' Is Outdated)
This page may contain some affiliate links. This means that, at no additional cost to you, Alpha Investing Group will earn a commission if you click through and make a purchase. Learn more.
Asset allocation by age comes down to one famous rule, and that rule is quietly solving the wrong problem.
Subtract your age from 100 and hold that percentage in stocks. It fits on a napkin, it needs no software, and it puts a 29-year-old at 71% stocks, which is not a crazy place to stand. The trouble starts the moment you ask what the number 100 was ever meant to represent.
It was standing in for how long your money has to last. That number has moved. The rule has not. Here's what this guide covers:
- Where the rule came from, and the part of it that still works
- What your stock and bond split actually controls, and what it doesn't
- The specific number underneath the rule, and how far it has drifted
- A starting point built on years rather than birthdays, with a worked example
- The shortcut, if you would rather not do any of this yourself
- When to deviate, and how to rebalance without turning it into a hobby
None of this requires you to become an active investor. If anything, it requires less attention than you're giving it now.
Where the 100 minus your age rule came from
Nobody signed the rule into existence. It became the default answer to asset allocation by age during a period when the arithmetic behind it was roughly right, and then it outlived the arithmetic.
Picture the investor it was built for. They retired at 65 with a defined-benefit pension covering the floor of their spending, they were drawing on savings for maybe fifteen or sixteen years, and bond yields were high enough that a large bond position paid real money rather than just sitting there being calm. Holding 40% bonds at 60 was a sensible trade under those conditions. You gave up growth you didn't need for stability you did.
Every one of those conditions has changed for most people. Pensions have thinned out, retirements have stretched, and the person reading this is probably funding the whole thing themselves through a 401(k) and an IRA.
The market noticed. Kiplinger's write-up of the rule sets out the modern patches: subtract your age from 110, or from 120, and you land on a more aggressive equity allocation that supposedly fits longer lives. One adviser quoted there says the Rule of 100 "tends to be more conservative than I feel is needed."
That's an honest fix, and it's also a tell. When the response to a broken rule is to change the constant and keep the formula, the formula was never the thing doing the work.
Here's the part worth keeping. The rule is right that your mix should get more conservative over time, and right that the change should be gradual rather than a single decision you make at 65. Those two ideas are sound. It's the input that's wrong.
What your stock and bond allocation by age actually controls
Most people think their allocation controls their returns. It mostly controls how bad the bad years feel, and whether you're still invested when the good ones arrive.
The regulator puts this about as plainly as anyone. The SEC's beginners' guide to asset allocation says the mix that works for you "will depend largely on your time horizon and your ability to tolerate risk," and then gives the number that makes the point concrete: large company stocks as a group "have lost money on average about one out of every three years."
One year in three. Not a crash, not a crisis, just the ordinary texture of owning stocks. Bonds exist in your portfolio to make that texture survivable, and there are only two situations in which survivable actually matters.
The first is behavioral. If a 35% drawdown would make you sell, then a portfolio you can't hold is worse than a portfolio with lower expected returns, because the second one you'll still own at the bottom. That's risk tolerance, and it's a fact about you rather than about markets. It's also easy to overestimate before you've lived through one.
The second is mechanical, and it's the one almost nobody explains. When you're retired and selling assets to fund your spending, a bad year forces you to sell shares at a bad price, permanently. Those shares never recover, because you no longer own them. That's sequence of returns risk, and it's the actual reason a glide path steepens near retirement. Your capacity to absorb a bad year collapses the moment you start withdrawing, whatever you happen to feel about volatility.
So there are two different things here, usually dressed up as one. Risk tolerance is how much volatility you can stand. Risk capacity is how much your plan can absorb without breaking. Age tracks capacity loosely and tolerance not at all, which is a lot of weight to hang on a birthday.
The number the rule was built on has moved
Here is where the field goes vague. Every guide that calls the rule outdated blames longer lifespans, and then declines to say by how much. The number is public, and it's more interesting than the hand-waving suggests.
The Social Security Administration's Office of the Chief Actuary publishes it every year. In its 2026 actuarial note on life expectancy at 65, the cohort table shows how many further years a person reaching 65 in a given year can expect. Someone hitting 65 in 1980 could expect 16.9 more years. Someone hitting 65 this year can expect 20.5.
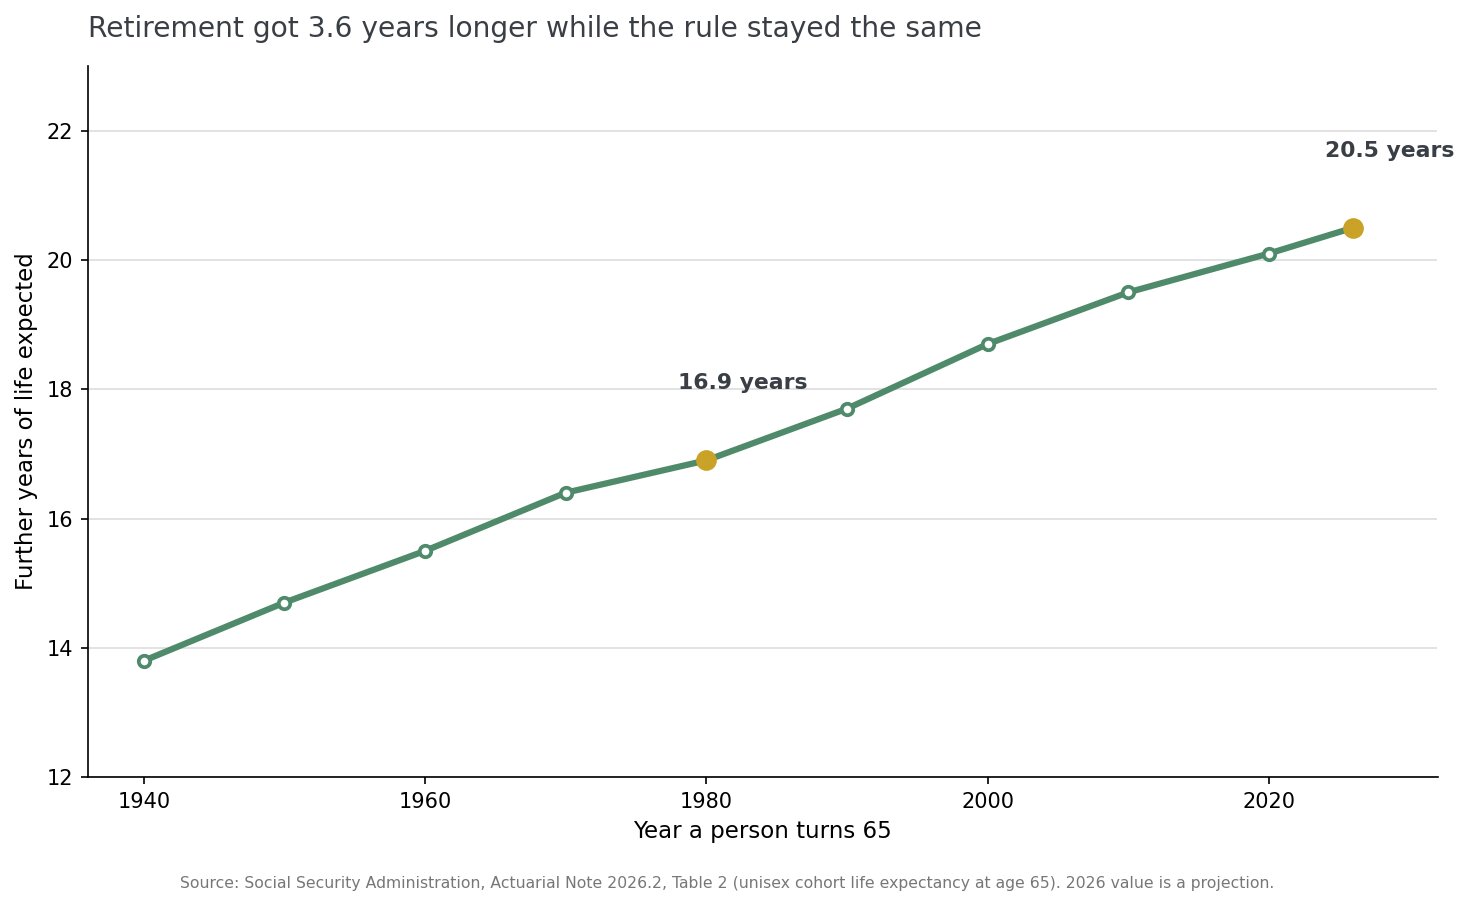
Figure 1: Rising life expectancy at age 65 over time.
That's 3.6 extra years, or a retirement roughly 21% longer than the one the rule was calibrated against. These are projections built on the 2026 Trustees Report assumptions, not observations, and averages hide enormous variation. Roughly half of people live longer than the number.
Now hold that against the arithmetic. A 65-year-old following the rule holds 35% stocks and 65% bonds, and has to make that pot last two decades and change, through inflation, with no pension underneath it. The rule tightened nothing to account for the extra years, because it has no mechanism for accounting for anything. It only knows your age.
I keep coming back to how odd that is. The most quoted allocation rule in personal finance takes exactly one input, and the input is the thing it least needs to know. Plenty of good rules of thumb survive on being roughly right. This one survives on being easy to say.
Count years, not birthdays
Swap the input. Instead of asking how old you are, ask how many years until you spend this money. Everything asset allocation by age was reaching for falls out of that question directly, and the answer is usually less conservative than your birthday implies.
First, notice that your horizon is longer than your retirement date. People treat 65 as a finish line where the money stops working. It isn't. You'll spend the first dollar around 65 and the last one somewhere in your late eighties, so the average dollar in your account is invested for far longer than the count to retirement suggests. A 29-year-old isn't investing for 36 years. They're investing for something closer to 48.
Second, separate the money by when you need it. A house deposit you'll use in three years and a retirement pot you'll start drawing in thirty-six are not one portfolio, even if they sit in the same brokerage login. Give each its own horizon and its own mix. The deposit belongs nowhere near an aggressive equity allocation no matter how young you are, and the retirement money shouldn't be dragged conservative because the deposit is sitting next to it.
Third, count the income you don't have to fund. Social Security, a pension, rental income, a spouse still working. Each is a bond-like stream you already own, which means your real exposure to a bad market is smaller than your balance suggests. Someone whose Social Security covers most of their fixed costs has more capacity for stocks than someone whose portfolio covers everything, at the same age, with the same nerves.
This is the idea behind lifecycle investing, and it's what serious glide-path design actually models. Vanguard runs saving rates, expected retirement ages and guaranteed income sources through a life-cycle model before it settles on a single percentage. Age is an input there, and nowhere close to the only one.
How much should you invest in stocks by age? Starting points, not prescriptions
You still need a number to start from. Here it is, organized by the thing that matters, with the ages most people map onto it.
| Years until you spend the money | Starting point for stocks | Typical age, retiring around 65 |
|---|---|---|
| 30 or more | 90-100% | 20s and 30s |
| 20 to 30 | 85-95% | Early 40s |
| 10 to 20 | 70-85% | Late 40s to 50s |
| 5 to 10 | 55-70% | Late 50s to early 60s |
| Drawing on it now | 30-55% | 65 and beyond |
These are ranges, not answers, and the right end of each range depends on your risk tolerance rather than your birthday. Sit at the low end if a rough year would genuinely make you sell. Sit at the high end if you've held through a real drawdown and know what you did.
Put that next to the rule and next to a professionally designed path, and the gap is not subtle.
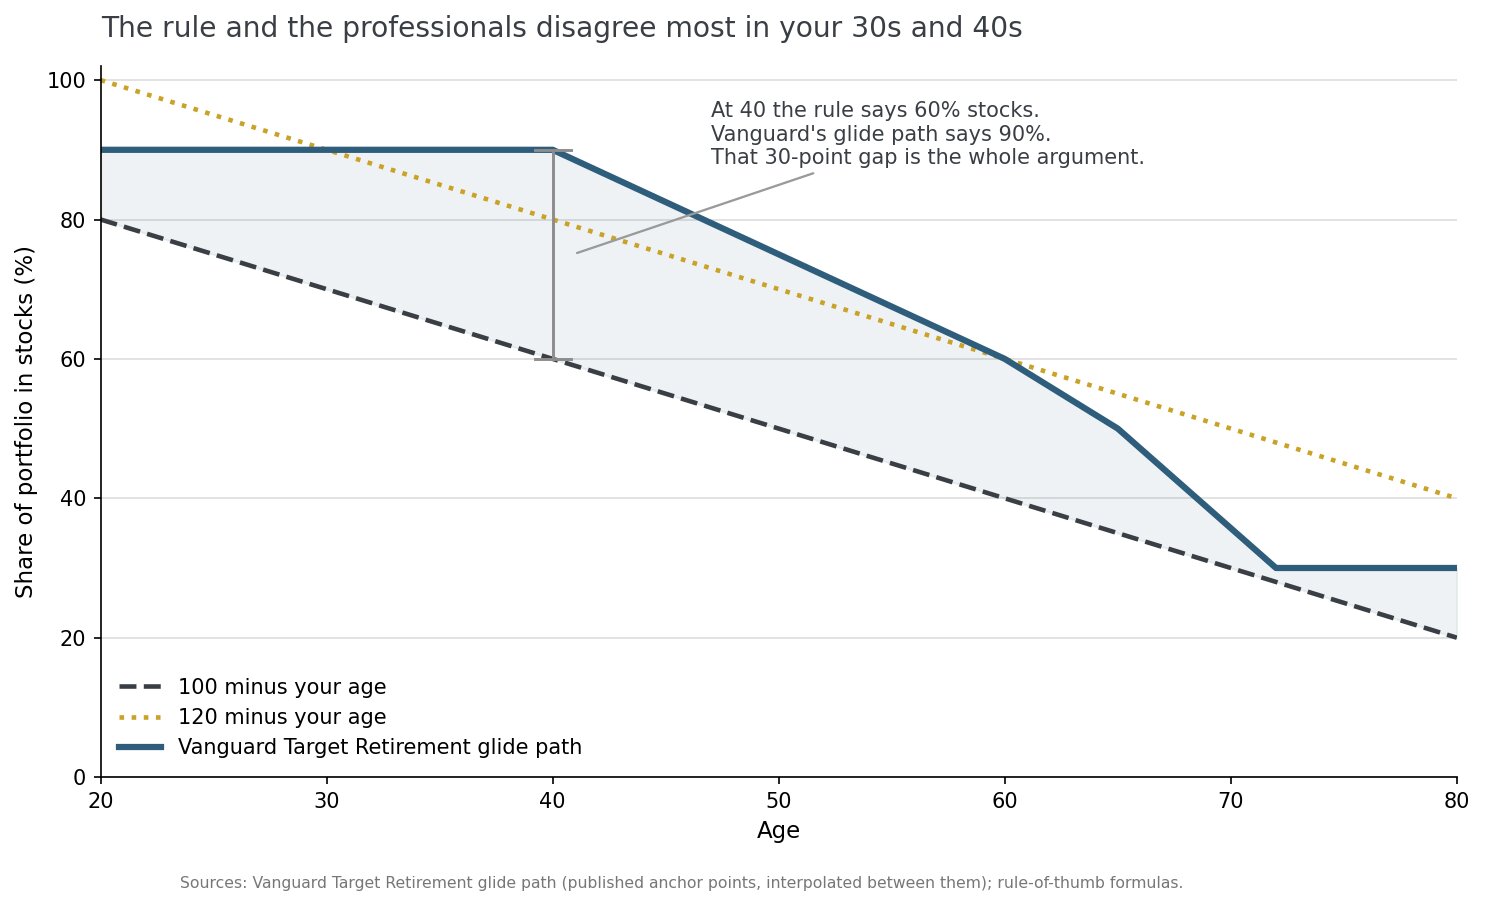
Figure 2: Comparing rule-of-thumb and target-date asset allocation by age.
Vanguard's published target-date glide path holds 90% stocks from age 20 all the way to 40, only then begins reducing, passes 50% at 65, and settles at 30% stocks and 70% bonds at 72, which its research identifies as the most common age to start withdrawals. The rule has you at 60% stocks at 40. The glide path has you at 90%. That 30-point gap runs straight through your best earning years.
Say you're 29, with $40,000 invested across a 401(k) and a Roth IRA, adding $600 a month. Your horizon on that money averages around 48 years, and you won't touch a dollar of it for 36. The rule puts you at 71% stocks and 29% bonds, which is $11,600 in bonds.
Ask what job those bonds are doing. They aren't protecting a withdrawal, because there isn't one for three and a half decades. They aren't managing sequence of returns risk, because you aren't selling anything. They're smoothing a ride nobody is watching.
That's the case for the higher number. The case against it is about you rather than the math: if holding 95% stocks means you check the balance daily and bail in March of a bad year, hold less. A mix you'll actually keep beats an optimal mix you'll abandon. If you're building the underlying portfolio from scratch, our guide to index investing and the rules for a diversified portfolio cover what goes inside each side of the split.
The shortcut: let a target-date fund run the glide path
If everything above sounds like more decisions than you want to make, there's a version where you make one decision and stop.
Target-date funds do this whole exercise automatically. You pick the fund with the year closest to your retirement, and the manager runs the glide path for you, shifting the equity allocation down over decades and rebalancing along the way. You never place a trade. You never have to remember what your target mix was supposed to be.
This is not a fringe option. Vanguard's How America Saves 2026 reports that 96% of plans now offer target-date funds and 69% of participants sit in a professionally managed allocation. If you have a workplace plan and you've never chosen your investments, there's a good chance you're already in one. Worth checking before you build anything.
Two honest caveats. The fund is designed for the average investor retiring in your year, so it can't know about your pension, your rental income, or your plan to work until 70.
The second one is more useful than it sounds. A fund's date refers to when you'd stop working rather than when you'd spend the last dollar, which makes picking a later-dated fund a legitimate way to hold a more aggressive mix without managing it yourself. Someone retiring in 2060 who wants more stocks can hold the 2065 fund.
I have mixed feelings about how well this works. The precision loss is real, and there's something slightly uncomfortable about handing the decision to a model built for an average person who isn't you. But the alternative assumes you'll keep doing the maintenance for forty years, and most people don't. The SEC calls these lifecycle funds and describes them as one-stop shopping. That's about right, and for most people it's the better trade.
When to deviate, and how to rebalance once a year
Deviating from the starting point is fine. Deviating for the wrong reason is where the damage happens.
Four reasons to sit away from the table above:
- Guaranteed income covers your fixed costs, which gives you more capacity for stocks at any age.
- You've been tested and you know your real risk tolerance, so you can adjust toward what you actually did in the last downturn rather than what you think you'd do.
- You have a large goal coming up in the next few years. Carve it out, give it its own short horizon, and leave the retirement money alone.
- You're still working and have no plans to stop at 65, which makes your horizon longer than your age suggests.
Bad reasons: the market feels expensive, a headline scared you, someone on the internet said bonds are dead, or your balance had a good year and you want more of what just worked. None of those are horizon changes.
Then there's rebalancing, which keeps the whole thing honest. A 90/10 portfolio doesn't stay 90/10. A strong year in stocks pushes it to 93/7 and quietly raises your risk without you deciding anything.
The SEC's guide lists three ways to fix that: sell from the overweight side and buy the underweight side, buy only into the underweight side with new money, or redirect your ongoing contributions until the balance comes back. In a 401(k) that's still in the accumulation phase, the third method usually does the job on its own and never triggers a sale.
Do it once a year. The same guide notes that rebalancing "tends to work best when done on a relatively infrequent basis," which is a polite way of saying that people who rebalance constantly are trading. Pick a date you'll remember, check the split, correct it if it's drifted more than about five percentage points, and close the tab. Our walkthrough on portfolio rebalancing covers the mechanics and the tax wrinkles in a taxable account.
One last thing about the end of the path. Your allocation is only half the retirement question. The other half is how much you draw, and the 4% rule and its limits is where to start on that.
In summary
The rule isn't stupid. It's just answering a question about your age when the question you needed answered was about your calendar.
- The rule's premise moved and the rule didn't. Life expectancy at 65 has gone from 16.9 further years in 1980 to 20.5 today, and the formula never adjusted.
- Your split controls drawdowns rather than returns. Bonds buy you stability, and stability is only worth paying for when you're about to sell or when you'd otherwise panic.
- Count years, not birthdays. Work from today to the day you'll actually spend the money, and remember your average dollar sits far longer than the count to retirement suggests.
- Start from the table, then adjust for guaranteed income and for a risk tolerance you've actually tested. Market forecasts don't belong in that adjustment.
- Or skip all of it. A target-date fund runs the glide path for you, and most workplace plans already offer one.
- Rebalance once a year, using new contributions where you can, then leave it alone.
If you take one thing from this, make it the swap: stop asking what mix suits a 29-year-old and start asking what mix suits money you won't touch for 36 years. Same person, better question.
Frequently asked questions
Do I have to base my asset allocation strictly on my age?
No, and you shouldn't. Asset allocation by age is a proxy for time horizon, and it's a loose one. Two 55-year-olds, one retiring at 60 with no pension and one working to 70 with a pension covering their fixed costs, have very different capacity for stocks despite matching birthdays. Use age to get in the right neighborhood, then adjust for horizon, guaranteed income, and how you actually behaved the last time markets fell.
Do I need bonds at all in my 20s and 30s?
Very few, and possibly none. Vanguard's glide path holds 10% bonds at 20, which is a deliberate choice rather than an oversight. That sliver gives you something to sell into a crash so you can buy stocks cheap without adding new money. Against it: over a 40-year horizon the drag is real and the protection is protecting nothing. If you hold zero bonds, be honest about whether you'll sit through a 40% drop. If you're not sure, 10% is a cheap insurance policy against your own behavior.
How often should I rebalance, and will it trigger a tax bill?
Once a year is plenty, and a drift threshold of around five percentage points is a reasonable trigger. Inside a 401(k), IRA or Roth IRA, rebalancing has no tax consequence at all, so you can adjust freely. In a taxable brokerage account, selling an appreciated holding can create a capital gain, which is why directing new contributions to the underweight side is usually the better first move. If you have to sell in a taxable account, check the holding period and consider whether a tax professional should look at it first.
What if I have a pension or expect Social Security? Does that change my mix?
It changes it more than almost anything else on this page. Guaranteed income covering your fixed costs behaves like a very large bond position you already own, which frees the portfolio to carry more equity risk than the balance alone would suggest. If Social Security and a pension cover your housing, food and healthcare, a bad market year threatens your discretionary spending rather than your rent, and you can reasonably hold more stocks than the standard tables imply. Work out what share of your essential spending is already covered before you set the number.